“You can’t eat a brick” is one of my most quoted catch phrases and may seem a bit odd, given I am writing for a property magazine.
During divorce, many people focus on retaining the family home, almost at all costs, forsaking other assets. Whilst having somewhere to live is number one priority for both parties, what are the implications of staying in the house? Whilst on the face of it, it provides stability for the children, costs can be saved by staying and it just “feels good” to stay.
So you decide to stay, trading pensions and other assets to buy your ex out, what are the implications of this? Can you afford to not only maintain the family home; the mortgage, if you have one but what are the costs of foregoing other assets, for example a pension.
Using a modelling tool, you can very quickly ascertain the financial implications of a decision and make a more rational decision, which may be unexpected. One retired couple I worked with had made the decision for him to stay in the house, they had a range of assets and from the modelling, we were able to see that he would run out of money within four years. Yes, he still had the house, could downsize or equity release, but he would be four years older and the decision would be forced. Thankfully they were able to make an alternative decision before it was too late. Staying in the home may feel safe but at what cost?
3% of people take financial advice during divorce, 97% of people wished they had.
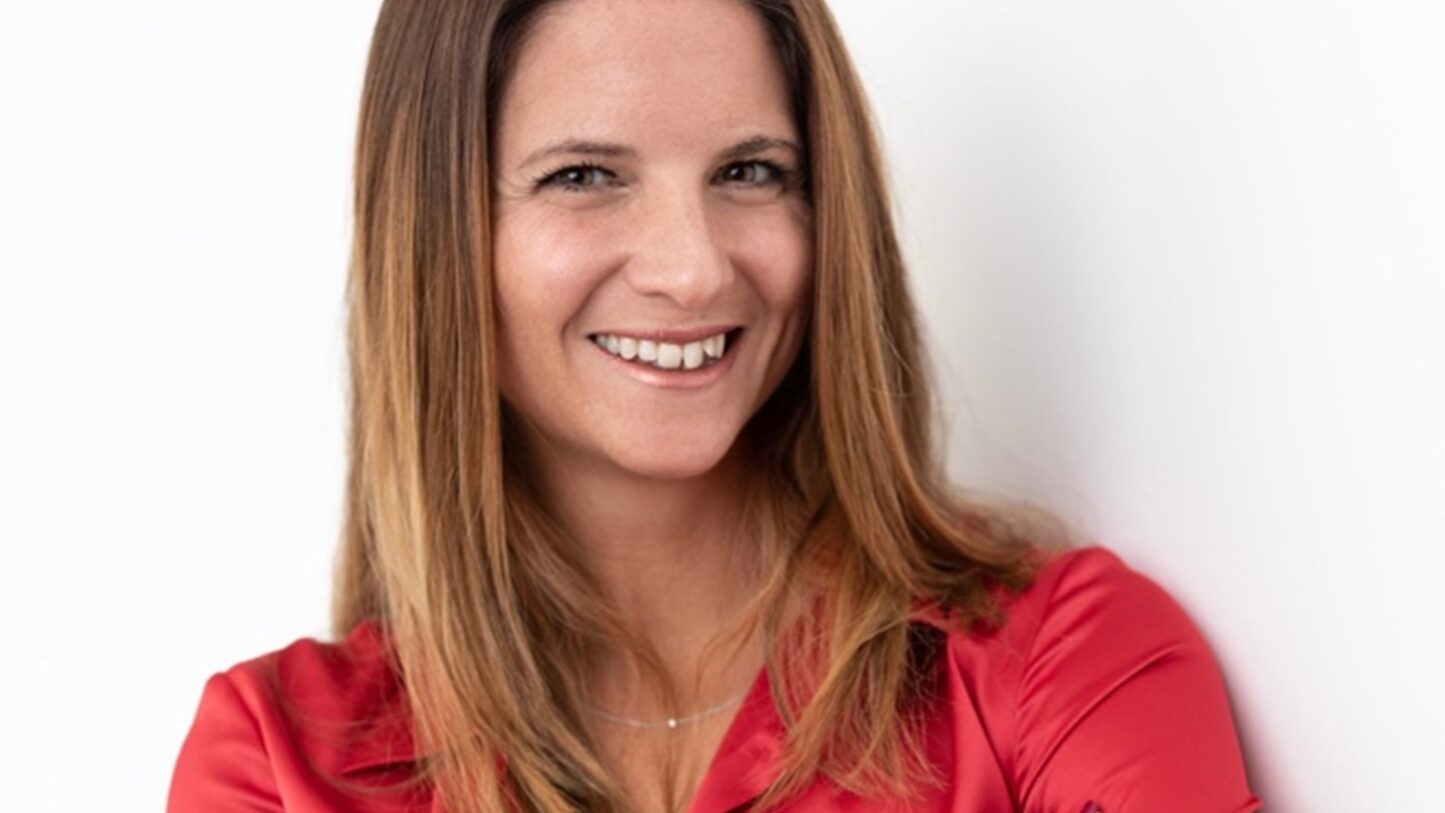
Jayne Wildish,
Jaynewildish.co.uk; jayne@jaynewildish.co.uk; 07826847175; LI Jayne Wildish (Instagram divorcehelpuk)